Deadline Tracking Systems for Multi-Client Tax Practices
Automate recurring deadlines and dependencies before adding AI to prevent missed filings.
Deadline tracking systems for multi-client tax practices solve a workflow problem. Solo tax practitioners and enrolled agents who want to grow without hiring need to link how they create deadlines, collect documents, assign ownership, and record completion before they add AI. Predictive risk scoring can then focus attention on returns most likely to slip, but it cannot replace those foundations.
Why deadline tracking breaks down as a tax practice grows
A partner juggling hundreds of returns depends on a staff accountant to update the shared sheet before moving to the next file. During March–April compression, that update competes with preparation, review, and client questions. The sheet falls behind at the worst moment. This is not primarily a failure of diligence, because the process requires spare attention precisely when attention is scarcest. Manual tracking becomes least dependable when the practice most needs it.
A single client can generate federal and state income returns, quarterly estimated payments, pass-through entity returns, trust returns, and FBAR filings. Hundreds of clients therefore mean thousands of deadlines to track. Extensions add another wave in August–October, after the urgency of the original filing season has passed. A process built around remembering to inspect dates has no dependable way to absorb both that volume and the shift in seasonal attention.
The real cost of a missed deadline, beyond the IRS penalty
A missed deadline creates costs across regulatory exposure, internal labor, and client attrition. The IRS failure-to-file penalty applies a percentage of unpaid tax per month, up to a statutory limit, separately from failure-to-pay penalties and interest. State penalties can add to federal exposure for multi-state clients. The liability belongs to the client, but the relationship damage lands on the firm. Resolving the problem also consumes labor that could otherwise support current engagements.
A modelled 180-client practice illustrates the economics without requiring a large failure rate. Two missed deadlines per year, associated penalties, and one lost client produced losses that dwarfed the cost of automation. The lost relationship changes the calculation substantially. A penalty event can prompt a client to review the firm's broader tracking limitations, putting future revenue at risk as well as the immediate engagement.
AICPA Professional Liability Insurance Program data (2024) shows that missed deadlines and statute-of-limitations failures account for a material share of accounting firm malpractice claims. That exposure makes deadline control more than an administrative convenience. A reminder records that attention was requested. The design requirement is therefore to connect alerts to ownership, escalation, and evidence of completion, rather than simply increase how often reminders arrive.
What makes state and entity-type variation so hard to absorb manually
Federal filing dates establish a foundation, but they do not define the complete workload. Forms 1120-S and 1065 for S Corporations and Partnerships are due March 16, 2026, with extensions to September 15, 2026. Form 1120 for C Corporations is due April 15, 2026, with extension to October 15, 2026. Individuals and Schedule C filers also have an April 15, 2026 deadline, with extension to October 15, 2026. Those dates establish only the first scheduling layer.
Federal quarterly estimated payments add April 15, June 15, September 15, and January 15, 2027, while states may use different dates. State individual filing deadlines also diverge, including Virginia on May 1, Delaware on April 30, and Louisiana on May 15. Extension rules are not uniform either. Some states give automatic extensions, but others need separate filings for S Corporations and C Corporations. Composite nonresident filings and pass-through entity elections add jurisdiction-specific obligations that cannot be inferred from the federal return alone.
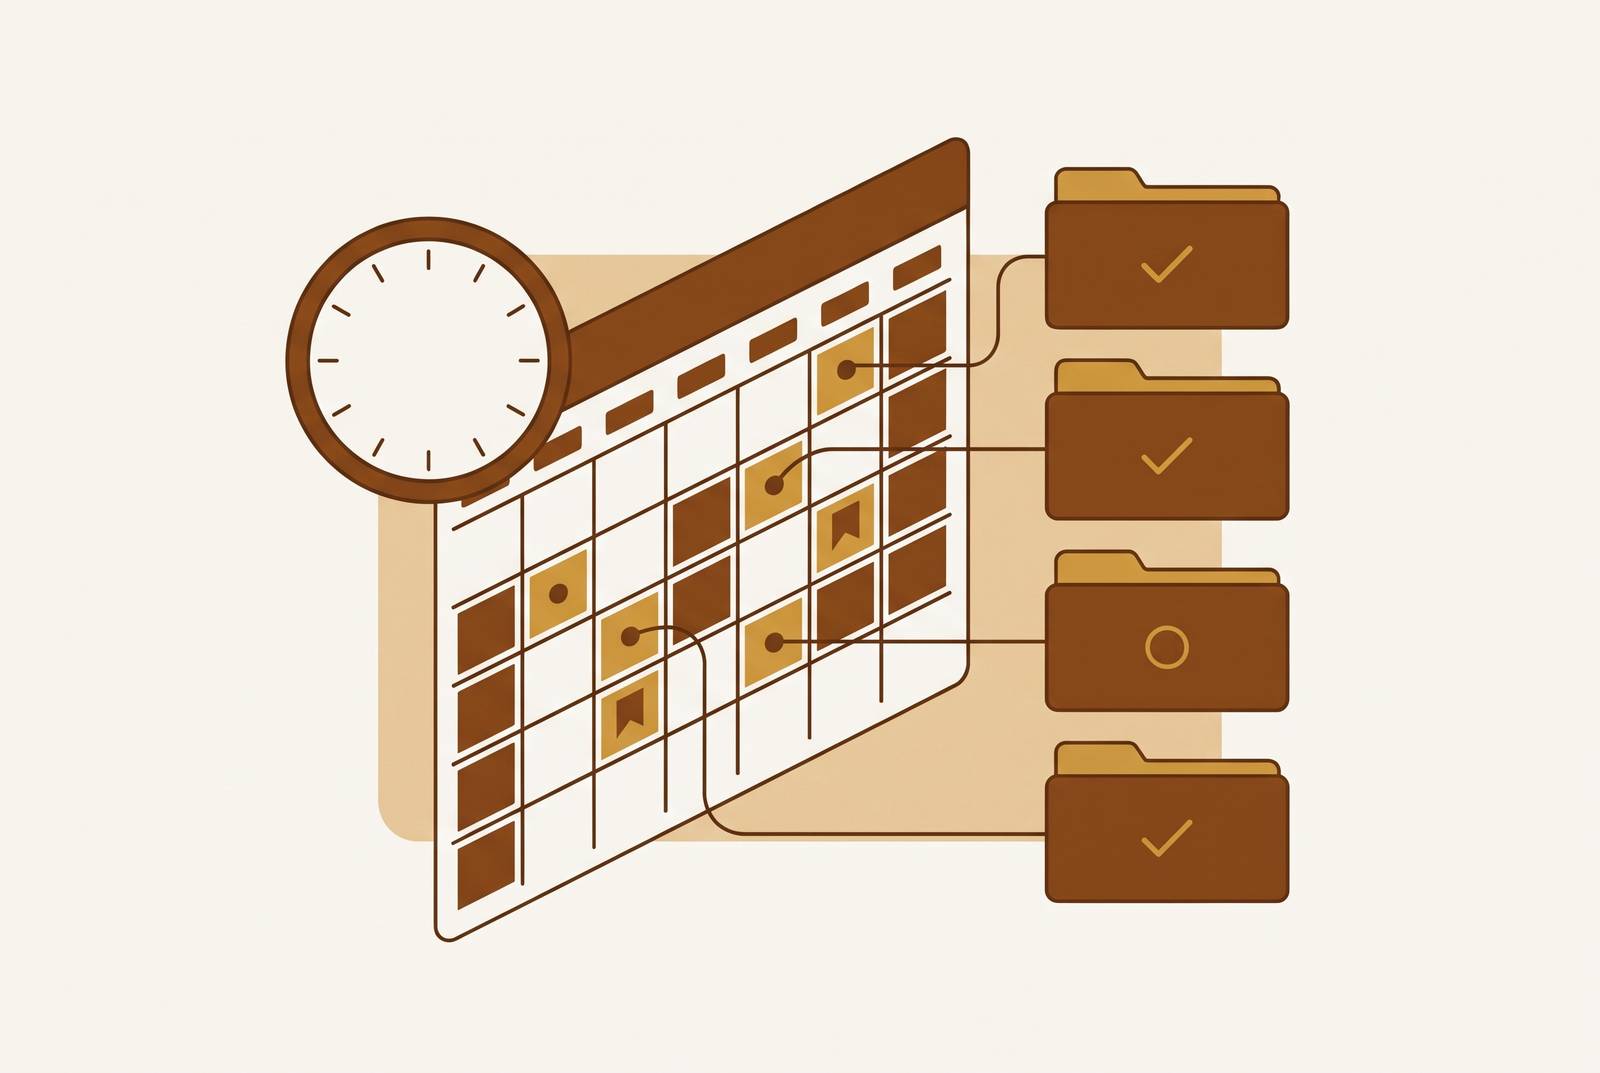
Dependencies make this more than a classification problem. A partnership K-1 must be issued before an individual partner's return can be prepared, so delayed partnership work cascades downstream. A calendar may show both deadlines without showing how one depends on the other. Legislative changes can also shift obligations mid-year, which requires ongoing monitoring. To track deadlines reliably, the system must show which rules apply to each client and which unfinished work holds up the next return.
The four functional layers a reliable deadline system must have
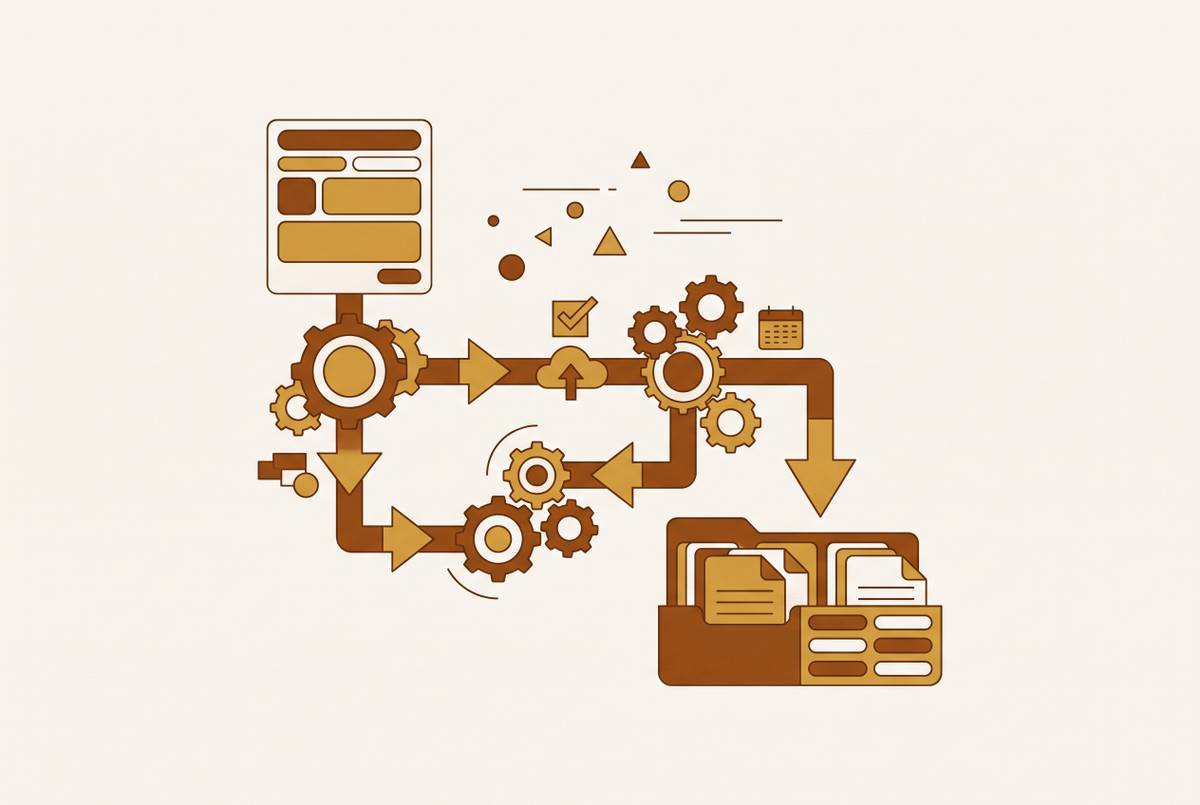
Workflow automation is the first layer, covering recurring task generation, dependencies, and status. Deadlines should recur automatically each year for the same client and engagement type. Preparation must precede review, and partnership work must connect to the affected K-1 recipient's return. Each obligation also needs a state, including not started, in progress, waiting on client, in review, filed, or extended. A date alone cannot describe the work.
Client data collection is the second layer because a return can have the right date on the schedule and still be held up by missing documents. Automated requests should ask for what is needed for a specific filing. Client management supplies the third layer through a centralized record of entity type, state nexus, responsible preparer, engagement history, and open deadlines. Together, these layers preserve the context behind a task. When a preparer is absent or overloaded, another team member can pick up the thread without reconstructing the engagement.
Capacity management completes the design by showing who is overloaded and who has room to take work. Separating preparation, review, and partner sign-off by function rather than by individual allows seasonal capacity to flex without making one person a single point of failure. Even for a solo practitioner, keeping the work stages separate helps because each takes time from the same person. The decisive test is whether each deadline connects to the client, service, work stage, responsible person, and evidence of completion. An alert without those connections is only a prompt.
How deadline systems mature from ad hoc to automated, and where most firms actually sit
Individual calendars and memory place deadline control with each practitioner, making coverage dependent on personal attention. Shared spreadsheets and tickler systems improve visibility but still require someone to maintain and inspect them. The burden remains with the people using them. Most firms occupy a middle position in which tracking has reduced missed deadlines without eliminating them. The remaining gap concerns how work moves through the process.
Practice management software with built-in reminders moves recurring calendar ownership from a person into the system. That change helps prevent common errors such as missed extension filings and confusion over state deadlines. A reminder can fire while the task is still unfinished, so the next stage adds automated triggers, escalation, and confirmation. Logging reminders, client responses, and escalations creates an audit trail that supports evidence of due professional care.
The 180-client model also illustrates why uniform monitoring is insufficient. Its manual process treated every client identically, while an AI-designed system identified a small subset of complex multi-entity clients responsible for most missed deadlines. Those clients were checked each day and had auto-escalation. This is a design distinction rather than a confirmed post-implementation performance result.
How to choose between a workflow tool and a full practice management platform
The buying decision begins with the scope of the operational gap. If recurring task management and internal due-date visibility are the only needs, a focused workflow tool offers a lighter approach with lower cost and faster setup. Jetpack Workflow fits that recurring-workflow and deadline-tracking use case. It is not a substitute for a full client portal or capacity management. Where document collection, billing, and client communication also need attention, additional tools may increase the total cost of that approach.
A full practice management platform is more appropriate when missed deadlines are one symptom of disconnected operations. The relevant criteria are coverage of workflow, client data collection, client management, and capacity. Geographic scope changes the requirements as well. Thomson Reuters ONESOURCE Calendar pre-populates regional tax deadlines and updates for regulatory changes across global income tax, VAT, and statutory reporting obligations. BrightManager lets UK-based firms create tasks and send client requests automatically, and its built-in Insights Hub shows how much work they have room to take on.
General automation tools such as Zapier, Make, n8n, and in-house scripts represent another route, but their connections can become fragile at peak load. Generic project management software also needs someone to set up how it handles entity types, jurisdictions, and extension rules. That configuration needs maintenance as rules change. Purpose-built tax tools encode specialized logic that would otherwise become the firm's responsibility. For solo practitioners, the useful comparison is therefore how much recurring coordination each option removes.
Where AI changes what a deadline system can do
A rule-based scheduler acts on a date or a set trigger, while predictive scoring uses patterns in how clients behave to find returns likely to miss their deadlines. This creates a basis for earlier intervention where the risk is developing. It extends the layered workflow.
AI systems built for tax practitioners are designed for their intake, document review, and compliance workflows. That focus makes them the category best positioned to combine predictive scoring with the entity-type and jurisdiction logic required for tax deadlines. An AI capability has limited value for deadline control if the underlying process cannot connect a risk signal to the responsible person and the affected obligation. The centralized client record and workflow states remain prerequisites.
For an enrolled agent seeking growth without employees, this narrows what AI should be evaluated to do. Predictive scoring does not establish that any named product will support a particular client volume, revenue gain, or working week. A defensible choice therefore rests on workflow fit and supported capability rather than a promise that AI alone removes busy-season constraints.
How to build the system in practice, starting from where most firms are now
The implementation sequence is to centralize first, automate second, and add predictive capability after the underlying records and workflows are dependable. A firm starting with shared spreadsheets should first map every client's entity type, state nexus, and filing obligations into a single record. That record must cover income tax returns, estimated payments, extension filings, and ancillary returns. This is the foundation for every later step. The database should be refreshed annually, with monitoring for legislative changes between annual updates.
Once that foundation is in place, onboarding should create records for all deadlines that apply to each new engagement, even those that start mid-year. Alert and escalation sequences can then operate against a complete set of obligations. Extended returns need their own trigger sequence. Treating them as a second engagement avoids leaving them as footnotes to the original filing season. Every alert, client response, and escalation should be logged against the client record so that the process leaves evidence of what happened.
The next step is explicit ownership supported by capacity visibility. Preparation, review, and partner sign-off should be separated by function, allowing work to move to someone with capacity when the assigned person is unavailable. A live status dashboard should show all open filing obligations and expose bottlenecks before a due date is at risk. For a solo practice, ownership remains with one person, but stage visibility still reveals where work is waiting. Automation cannot remove that constraint, but it can reduce reliance on memory to see it.
Finally, clients should be segmented by complexity and document-response history before monitoring becomes more selective. Clients with multi-entity structures, multi-state nexus, and a history of poor response rates need more frequent checks and earlier escalation than those with straightforward individual filings. Predictive capability can build on that differentiated process. The endpoint is a system in which ownership, status visibility, and escalation no longer depend on someone remembering to look.