Automating Client Intake for Tax Firms Without a Dedicated Admin
Eliminate the intake bottleneck by automating the tasks that steal preparer time.
A solo preparer sends four separate emails after an engagement letter goes out, one asking for a missing W-2, one confirming an address, two just following up on silence, and is now on day three waiting for bank statements that a client has already forgotten to attach twice. For a solo preparer without a dedicated admin, client intake automation is the only mechanism that can keep onboarding consistent at scale, and this article walks through the practical stages of building that system so the preparer's time goes to the work that actually requires a preparer.
Intake problems in firms without a dedicated admin
In a firm with no dedicated admin, every intake failure lands directly on billable time rather than on a support role built to absorb it, which changes the nature of the problem. Every hour spent chasing a missing W-2 or re-entering a client's EIN is an hour not spent on advisory work, the work only the preparer can do. Tools built for tax research and drafting, Marble among them, can speed up what happens after intake, but they only pay off if intake itself doesn't consume the preparer's day first. That is the structural condition the rest of this piece addresses: not a software gap, but a coordination gap that only an admin or an automated system can close.
Intake automation, from first contact to engagement kickoff
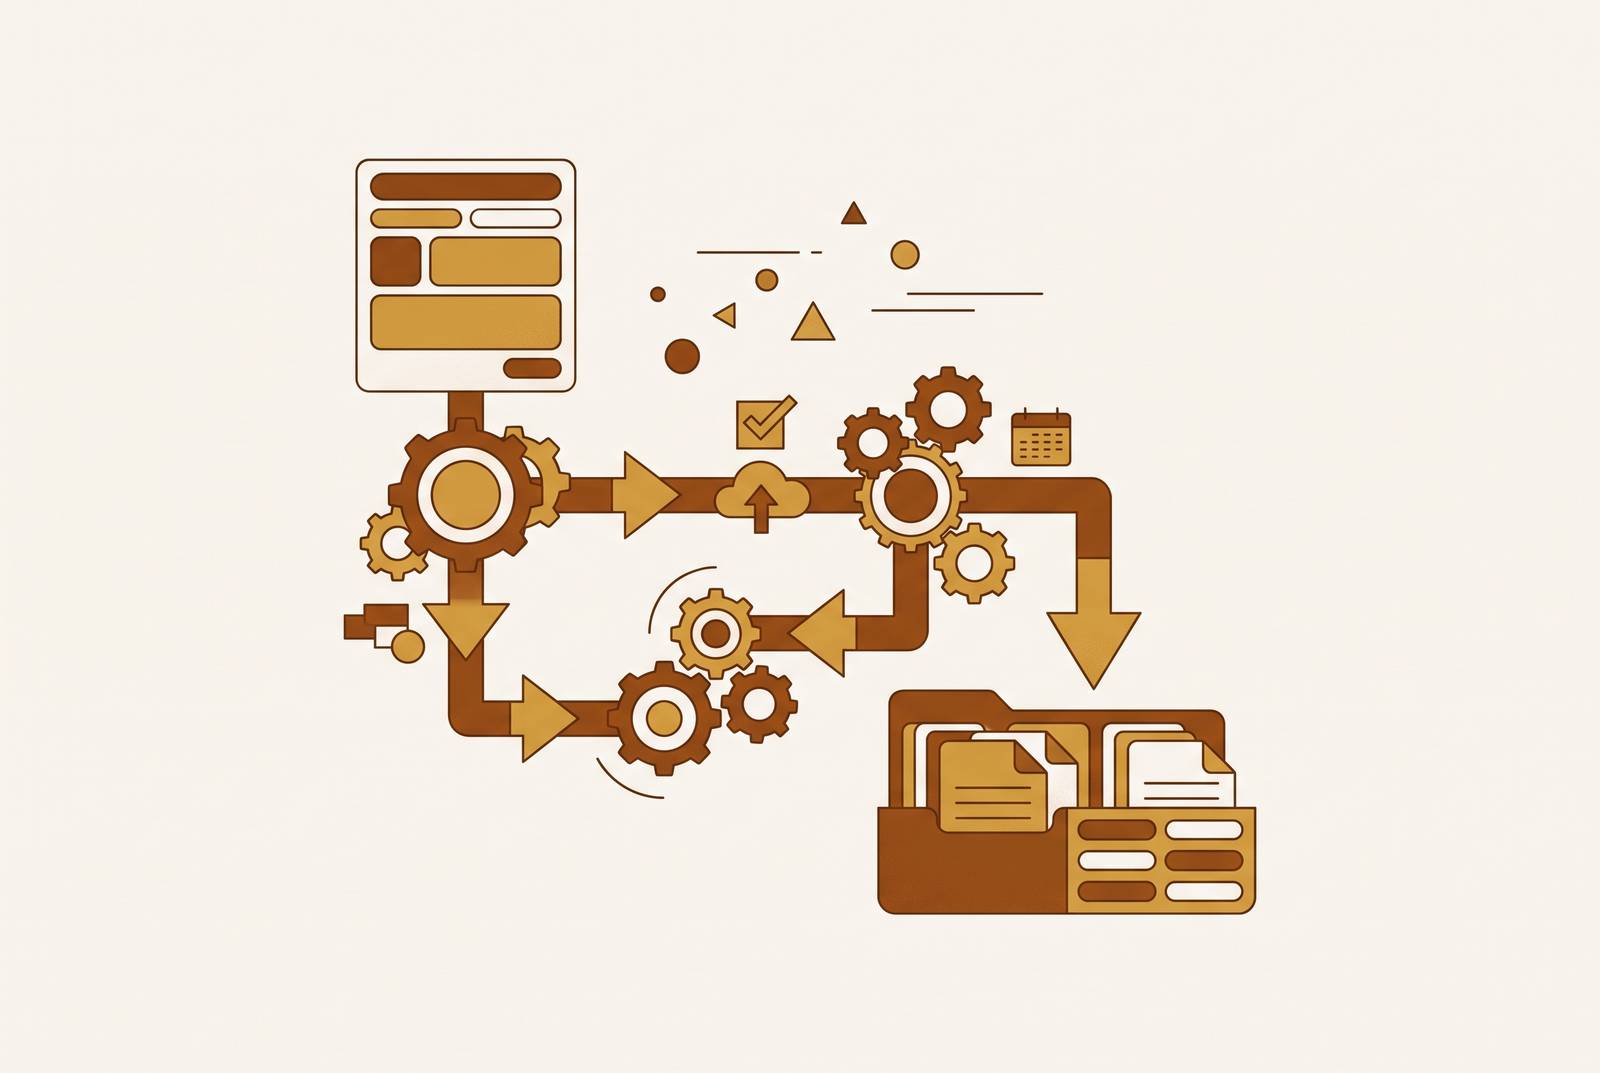
Intake automation is a four-stage sequence, collect, verify, sync, confirm, that runs continuously from the moment a prospect first makes contact to the moment a preparer receives a complete, routed file ready for work. The collection stage gathers structured client data through a web form, not an email thread. The verification stage confirms identity and executes engagement paperwork before any staff member reviews a document. In the sync stage, that verified record gets pushed into practice management software without anyone re-keying it. The confirmation stage closes the loop, telling both the client and the preparer that the file is complete and assigned. Running alongside all four stages is the phone channel, a separate and parallel intake stream: prospects and existing clients call in with questions, document routing needs, and appointment requests, all of which land back on the preparer's desk if nobody else is handling them. Tax firms face six phone peaks a year, not one, because every federal deadline brings its own surge, and each surge arrives exactly when preparers have the least spare time to pick up the phone. That channel deserves its own treatment later in this piece; for now, a complete intake system has to account for it, since the web form alone doesn't cover it.
Building the intake form so it collects the right data without overwhelming the client
The job of the intake form is to ask each client what their engagement requires, and nothing beyond that. Conditional logic is what makes that possible without a firm having to build and maintain a separate form for every client type it serves. A handful of core fields apply across the board: legal name, entity type, engagement type, prior accountant contact, and preferred communication channel. The form.submitted event generated by that single submission triggers the entire downstream workflow, so errors in these fields at the front end propagate through every stage that follows.
From there, the form should branch. An individual filer needs fields for Social Security number, filing status, dependent changes, and W-2 or 1099 income sources. If a client selects a particular business entity type from the entity type field, they should automatically receive an entity-specific engagement letter template and a matching document checklist, not a generic packet that leaves out half of what the engagement actually needs. The same branching logic that keeps a tax form focused is the logic behind how AI-powered tax research platforms like Marble surface only the statutes and regulations relevant to a client's specific situation, rather than returning a flood of material the preparer has to sort through manually. In both cases, the principle is the same: show the client or the preparer only what applies, and the system holds its value.
Forms that overwhelm clients are forms that get abandoned partway through.
| Engagement Type | Key Documents Requested | |---|---| | Individual | W-2s, 1099s, prior-year return, dependent documentation | | Business | EIN confirmation, officer list, payroll summary, fiscal year records | | Bookkeeping | Bank statements, prior ledger exports, chart of accounts | | Audit | Supporting schedules, prior correspondence, entity formation documents | | Advisory | Current financials, business structure summary, planning goals |
Once the form is submitted, it should fire an immediate confirmation back to the client containing a portal link, a checklist specific to their engagement type, and a document deadline. A client should never have to ask what to send or where to send it.
Running identity verification and engagement paperwork in parallel, not in sequence
You get the single biggest efficiency gain at this stage when you run identity verification and the engagement letter at the same time as document collection, instead of making the client wait for staff review before being asked to sign anything. Once form.submitted fires, Stage 2 should trigger automatically: a request for a government-issued ID upload, business verification for entity clients that confirms the EIN and reviews articles of incorporation, and an engagement letter countersignature request sent through e-signature, all without a staff member touching the file.
The engagement letter itself deserves more weight than it usually gets. It locks scope, billing terms, and client responsibilities, and generating it automatically from the entity type selected in Stage 1 prevents the manual version, one of the highest-error steps in traditional intake, from being skipped, delayed, or filled out incorrectly under deadline pressure.
This stage also sits on top of a real compliance layer. IRC Section 7216 makes it a federal misdemeanor to disclose tax return information without consent, so if an intake tool touches return information, it has to collect that consent before the data ever reaches it. For 1040-series clients, a compliant Section 7216 consent needs to be its own document, not a line buried inside an engagement letter, and Rev. 2013-14 prescribes its format, and the consent has to name the specific recipient and be signed before disclosure takes place. Purpose-built tax platforms are designed around this constraint from the start, but generic intake tools leave the firm to configure every one of these guardrails by hand.
Syncing the verified client record into practice management without manual re-keying
Pushing a verified, complete client record from the intake form into practice management software is where manual processes lose the most time, and where automation returns the most immediate benefit. This step should trigger on a defined threshold, typically once a client has uploaded a set percentage of required documents, rather than waiting on a staff member to check a shared drive and decide, on judgment alone, that the file looks ready.
Hand-entering verified clients into the practice management system is the second biggest cost in manual intake. A 12-person firm running document collection through a web form but still hand-entering every verified client into its practice management system has solved only the front half of the problem; the back half, routing, validation, and the handoff to billing, still consumes staff hours it can't spare.
Automating the phone channel: what an AI receptionist should and should not handle
Tax firms don't face one busy season on the phone; they face six. The fourth-quarter estimated payment deadline on January 15, 2027, extended returns on October 15, 2026, extended partnerships and S-corps on September 15, 2026, second-quarter estimates on June 15, the main filing season deadline on April 15, and partnership and S-corp returns on March 16 each bring their own call surge, and each one lands precisely when preparers have the least time available to answer.
An AI voice agent or receptionist can absorb that channel, handling new-client inquiries, appointment booking, document routing questions, and deadline reminders. The line between what it may say and what it must escalate is not a configuration preference; it is a legal boundary. Five scenarios are technically clean to automate today: identifying a client through a CRM lookup, checking status against practice software, routing a document question to the correct upload portal, sending a deadline reminder, and booking an appointment directly into the preparer's calendar. The greeting itself should tell callers directly not to share sensitive information on the line.
Section 7216 reaches the phone channel the same way it reaches the intake form: the AI should be configured to collect only scheduling details, and for anything touching an IRS notice, a return status question, or tax advice, it should take a message or book time with a partner. For a firm of 8 to 30 staff, a Famulor agent typically reaches production in four to seven business days, with the master-data connection to practice software completed on day 2 and calendar integration finished by day 3.
Stage 4: closing the loop with automated confirmation to client and preparer
A complete intake system ends with a confirmation that fires automatically to both parties, so neither the client nor the preparer has to wonder whether the file is actually ready. The preparer receives a task inside the practice management system with every document attached and the engagement kickoff checklist already populated.
This confirmation is also a natural trigger point for billing. Payment method collection and deposit capture can be built into the same workflow step, so the engagement is financially open before the preparer ever opens the file. The value of starting earlier compounds downstream: a slow intake compresses everything that follows it on the preparer's calendar, which makes the intake phase far more than a one-time administrative cost.
Choosing the right tools for each stage of the workflow
You should choose tools based on what each stage requires, not a vendor's marketing category. A form builder that excels at collection but drops its data at the edge of practice management has only solved one-quarter of the problem described above.
Three capabilities separate an adequate form tool from one that delivers the full workflow. Clean data handoff is the third: answers need to land structured and validated inside the tax workflow, not as a PDF a junior staff member has to re-key by hand.
Marble is built specifically for this workflow. It handles the full intake pipeline, collect, verify, sync, confirm, for tax practitioners rather than functioning as a generic accounting tool retrofitted for intake, and it spares the firm from manually configuring the Section 7216 compliance guardrails described earlier. Each of the four stages can fail independently, and a firm that automates only the front end still ends up manually routing files into practice management by hand; the sequence has to run unbroken so that when a preparer opens a file, intake is genuinely finished and the preparer can move straight into research and advisory work. For the phone channel specifically, OnceHub Phone Agents and Famulor serve different needs within the same compliance boundary, record-and-transcribe versus prompt templates built for regulated professions, and a firm's choice between them should follow from which capability it needs more.
Stakes raised by the IRS's workforce and legislative shifts
Clean, early intake is now a risk management posture, not just an efficiency gain. If firms complete intake accurately and early, they absorb less downstream liability at a moment when IRS processing is slower and the returns themselves have grown more complex. TIGTA reported that the IRS lost roughly a quarter of its workforce, shrinking from approximately 103,000 to 77,000 employees, and the National Taxpayer Advocate warned Congress that a contraction of that size, combined with more than 100 tax code changes, some retroactive, raises the risk of filing errors and delayed refunds.
Legislative complexity has pushed intake data requirements higher at the same time. The One Big Beautiful Bill Act drives dozens of major changes affecting the 1040, and intake questionnaires built before this legislative cycle are likely missing fields the return now requires. A firm still running last year's intake form isn't only working inefficiently; it is collecting incomplete data from the first conversation with a new client. A firm that starts prep six days earlier because its intake was clean and complete has more time, not less, to catch that new legislative complexity before the filing deadline arrives. Speed at intake buys back the time that a contracted IRS workforce has made more valuable.
A parallel risk runs through AI governance itself. The risk here is trusting an answer that isn't fully accurate, or pasting sensitive client data into a system that was never built to hold it.
The preparer's day with automated intake
Once intake runs on automation, a preparer's real engagement with a new client starts the moment the file arrives complete and routed, not three weeks and a dozen follow-up emails earlier, at the moment the prospect first made contact. That shift changes how the day is spent. At companies that haven't made that investment, the team stays in production mode handling work the system could have absorbed on its own.
Staff burnout carries a cost beyond the people experiencing it. If preparers spend their days firefighting missing documents, they have no bandwidth left for the advisory services that actually drive revenue growth and client retention. In a firm with full intake automation running, the phone is handled, new-client forms route themselves, documents get chased without anyone remembering to send the fourth email, and the file lands in practice management complete, verified, and assigned. The preparer's first action on a new engagement becomes reviewing a finished file, not sending another request for a prior-year return that should have arrived weeks ago. The chaos described at the start of this piece was a solved problem, and the solution doesn't require hiring an admin a small or solo firm can't yet afford.