How Solo Enrolled Agents Absorb Peak Season Volume Without Adding Headcount
Systemize intake and use AI to reclaim hours for advisory work.
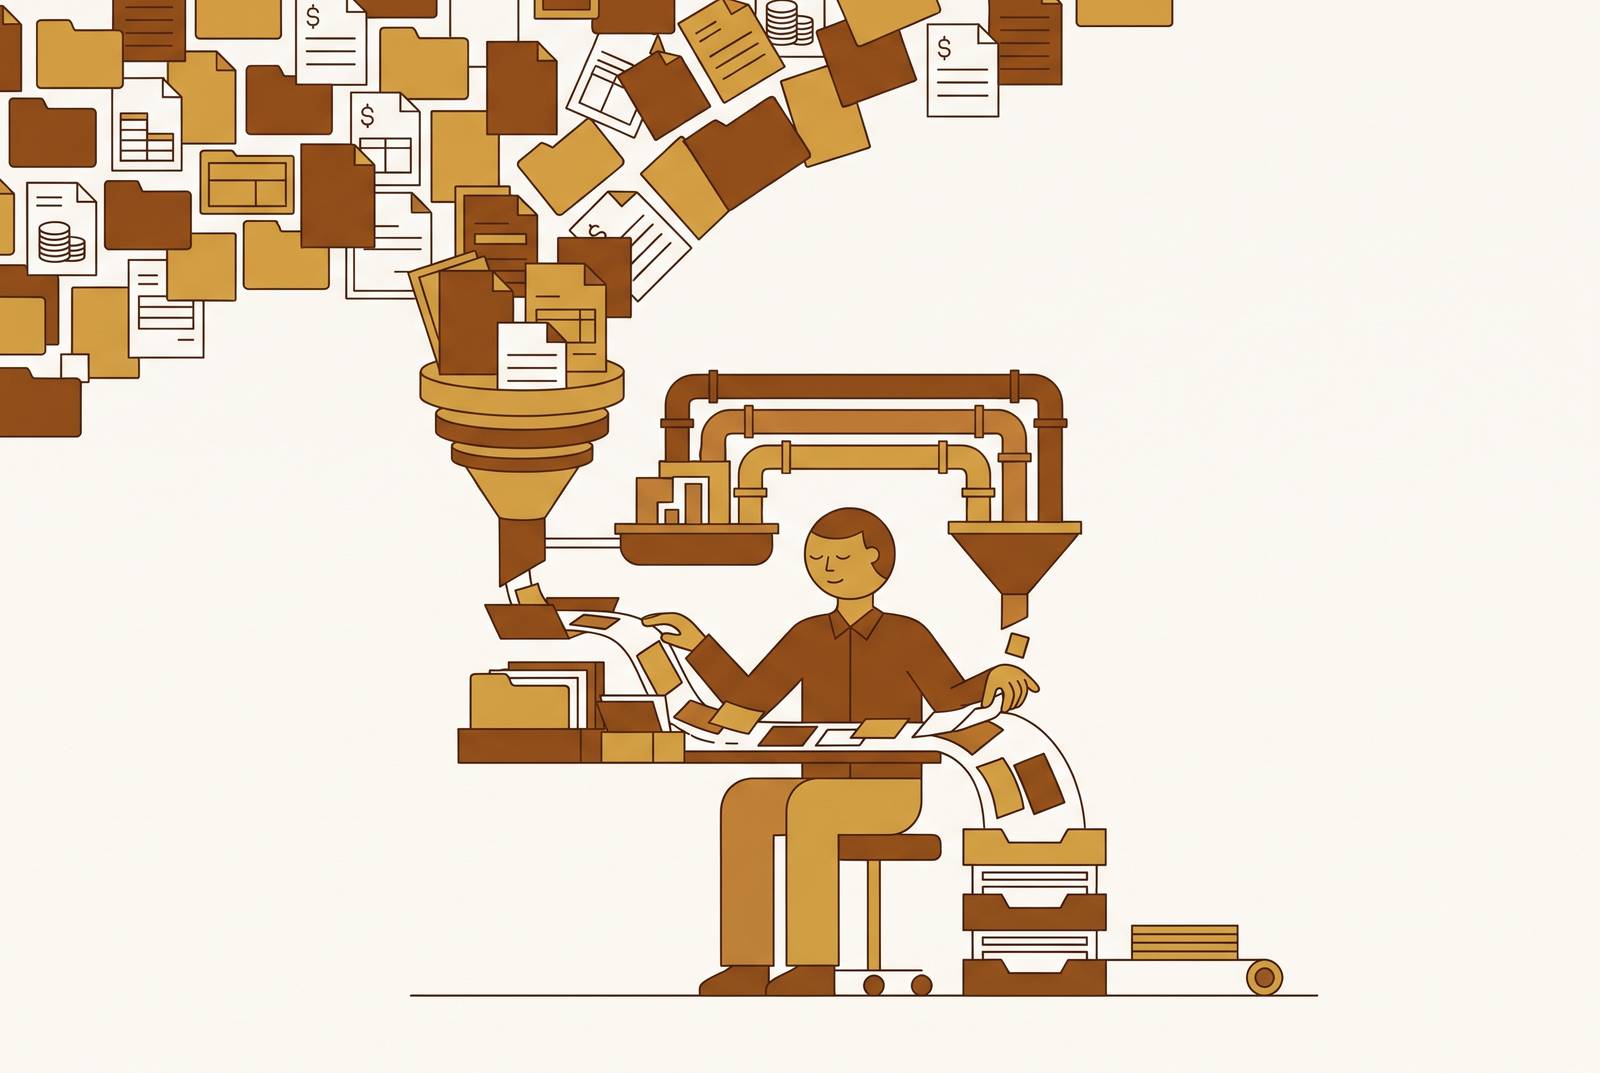
Solo enrolled agents can absorb peak-season volume without adding headcount by systematizing intake, using AI-assisted document review, and selectively outsourcing first-pass preparation while retaining professional judgment and sign-off. The structural advantage comes from removing administrative work from the EA’s schedule. Recovered hours can then support advisory work, allowing revenue to grow without adding more returns to the same compressed filing season.
Why solo enrolled agents hit a capacity wall that more hours cannot fix
A compliance-only practice concentrates most client work into the same filing season. Adding clients therefore adds hours precisely when the solo EA has the least room to accommodate them. The next filing cycle recreates the same compression, leaving income tied to the calendar even as the practitioner’s skill grows.
Seasonal hiring offers an imperfect escape from that pattern. IRS PTIN statistics count 71,966 credentialed enrolled agents nationwide as of September 2026, a thin pool from which to recruit licensed seasonal help. Hiring and training also take money and attention before demand peaks, but the need for that extra help drops when the season ends. The staffing expense outlasts its most useful window. For a one-person practice seeking growth without headcount, the answer must be process and system design rather than reproducing the same seasonal cost structure at a higher price.
Where the hours actually go during peak season
A solo EA’s season consists of two jobs layered together. One calls for the technical judgment of a licensed practitioner to analyze tax issues, weigh positions, and review completed returns. The other consists of document chasing, reminders, manual entry, intake triage, and completeness checks. Both compete for the same working day. The dominant drain is often the administrative surround, which consumes the practitioner’s attention before the technical work can begin.
A single 1040 client may send dozens of files as images, PDFs, and loose scans. Those files must be classified, checked for completeness, and reconciled before preparation begins. With that work to do for every client, it takes up much of the season without calling on the EA’s special skills. A CP2000 response drafted from scratch takes significantly longer than one developed through a structured AI-assisted workflow, and notices arrive on no predictable schedule.
A practitioner may have the knowledge to complete a return but lack the uninterrupted time and complete records needed to apply it. The workflow must separate administrative logistics from licensed work so that preparation and review do not wait on tasks that require no credential.
How intake tools let a solo tax preparer handle more clients without longer hours
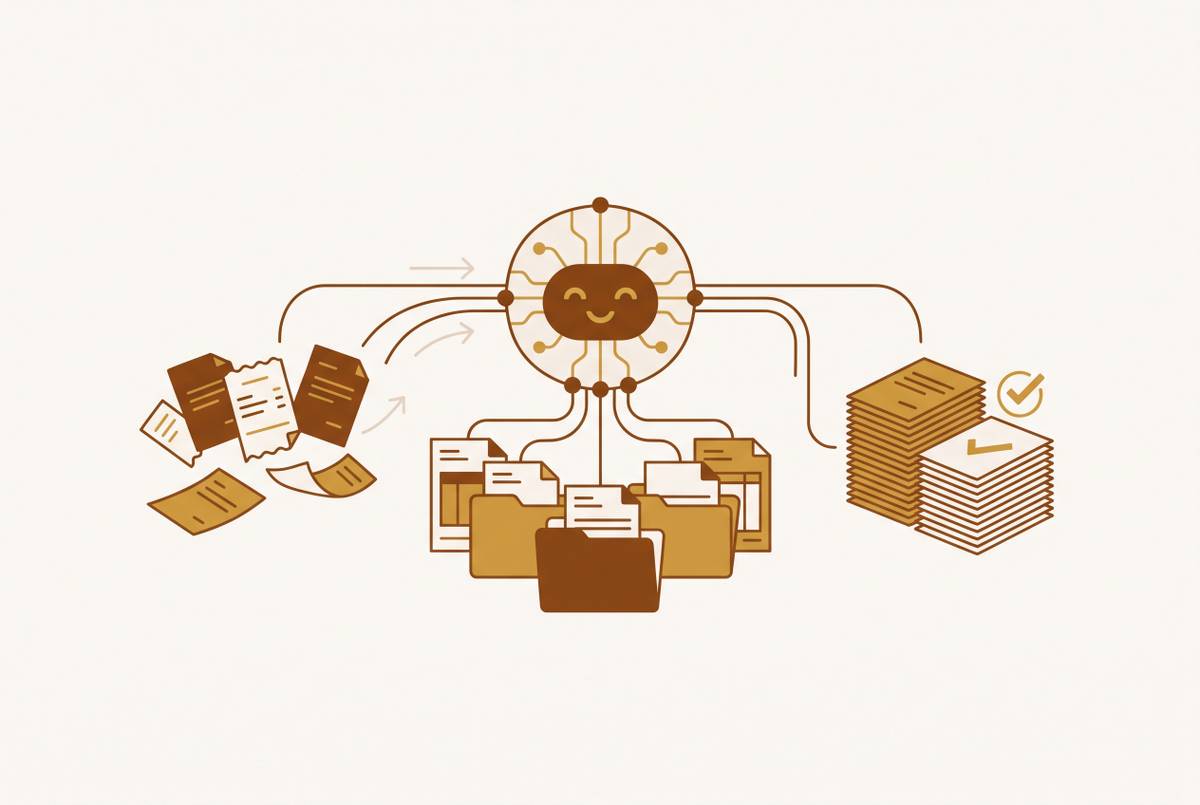
Intake is a design problem before it is a scheduling problem. Engagement letters, portal access, document request lists, completeness flags, and reminder nudges can form a structured onboarding sequence rather than a series of individually managed exchanges. That sequence compresses what used to be two weeks of back-and-forth into a much shorter window. The gain extends beyond faster document collection. With less follow-up to do, the EA can focus on work for longer stretches.
AI-assisted intake adds classification and missing-item detection to that sequence. The practitioner receives documents that have already been through an initial triage, saving the work of sorting each file by hand to see whether preparation can start. Practice management software then tracks jobs, deadlines, and client communications, making the sequence repeatable without relying on memory. This is where intake becomes a system. Once established, the process serves the same client volume more efficiently in later seasons rather than requiring another round of individual scheduling adjustments.
For a practice with fewer clients, lean preparation software and a basic portal may be enough, while mid-range practices need workflow tracking when keeping the work in order starts to hold it up. With more clients, the tools need to work more closely together so that data can pass between bookkeeping, preparation, and practice management without rekeying. Tool sophistication alone is not the goal. Where collection is the constraint, a portal and structured document-request workflow can recover more seasonal hours than a more sophisticated preparation engine.
How document review and compliance checks can be handled without the EA touching each one first
After intake, AI-assisted processing can shift the EA’s work from data entry to data validation. OCR-based classification handles an initial pass through source documents, while multi-year consistency checks flag anomalies against prior-year data. These functions move routine processing into the system and direct attention toward exceptions that require judgment. The practitioner still evaluates accuracy and completeness.
A structured AI-assisted workflow can produce a CP2000 response draft for verification and sign-off instead of requiring the EA to compose it from scratch. Total practitioner time can drop sharply because the starting point has changed. Drafting assistance gives the EA an output to examine critically, with professional attention reserved for its facts, reasoning, and support.
Circular 230 makes retained judgment central to this model. The licensed practitioner remains responsible for every position on a signed return, regardless of how the underlying information was processed. General-purpose AI tools can make up citations, so the practitioner must check every authority against the Internal Revenue Manual or the actual code section before relying on it. Automation therefore changes the work while leaving professional responsibility intact. Its value lies in moving irreplaceable judgment to validation rather than exhausting it on processing that a system can perform first.
Offshore preparation as a documented surge-capacity option for a one-person firm
More solo EAs are using offshore teams to draft returns and supporting workpapers while keeping review, signature authority, filing, and client relationships in-house. The model adds capacity at the preparation stage. It does not transfer professional liability or create more of the EA’s judgment, so its usefulness depends on how much preparation work is constraining the practice.
The compliance requirements are specific and non-negotiable. Preparers who outsource offshore must get client consent to share information overseas and follow IRC §7216, its Treasury Regulations, and the related data-safeguard requirements. The FTC Safeguards Rule also requires a written information security plan for all paid preparers, regardless of outsourcing model. These obligations are part of the operating cost. Offshore preparation is a documented, compliance-tested option for a one-person firm, but it is not a way to avoid responsibility for how client information is handled.
The onboarding advantage can be substantial compared with filling a domestic CPA role. An offshore team can already have handled a season’s worth of files by the time a domestic hire completes onboarding. If drafts reach the EA faster than the review queue clears, returns accumulate while awaiting sign-off. The model therefore depends on a strong reviewer and a structured review layer, supported by a competency that takes years to build and cannot itself be outsourced.
How the compliance stack should be built and what it costs per return, not per month
Software should be judged by its cost per return compared with fee revenue, with monthly subscription price as only part of the picture. Monthly pricing describes an expense without showing how much work it supports or whether it pays for itself. Cost per return supplies that context. A tool that removes repeated handling addresses a different economic problem from one that adds features without relieving the practice’s bottleneck. The comparison should therefore connect price to the workflow being changed.
A solo firm needs four distinct software layers, which are bookkeeping, tax preparation, tax planning, and practice management. No single product covers every layer. Bookkeeping and write-up hold client general ledgers and bank feeds, and their export into preparation software should avoid rekeying. Tax preparation helps with the return itself, while tax planning models what could happen in the future under different scenarios and entity structures. Practice management coordinates jobs, deadlines, invoices, and client portal access so that busy season does not depend on memory and email.
These layers need to be judged in different ways because each tackles a different drain on profit. For bookkeeping, the test is whether data gets to preparation without having to be entered again. For practice management, it is whether work, deadlines, and messages to and from clients stay in order. For tax planning, it is whether the software supports advisory work that preparation software does not create. AI-assisted classification, completeness checks, consistency checks, and drafting should be assessed against their particular processing tasks rather than treated as substitutes for the entire stack.
Professional suitability also comes before subscription savings. Enrolled agents who sign returns for pay must put a valid PTIN on every return and use software that has preparer signature fields. Consumer DIY products do not allow paid preparers to use them and do not have those required fields. They are not a lower-cost professional substitute. The written information security plan belongs in the stack’s operating requirements as well, before tools have been selected.
What the recovered hours are worth and why advisory is the right place to redeploy them
Compliance work is commoditized and price-compared, while advisory fees are compared with tax saved or the outcome delivered. That changes the fee conversation. A preparation-plus-advisory practice can achieve a higher average fee per client and effective hourly rate than a preparation-only practice. An advisory-balanced firm serving fewer clients can therefore gross more than a compliance-heavy firm with a larger roster.
Advisory also changes when expertise earns revenue. Planning engagements can occur in May, July, and October, filling months that compliance alone leaves empty rather than competing for the same filing-season hours. This addresses the original calendar constraint directly. The practitioner gains a route to growth that does not require every new engagement to pass through the seasonal preparation bottleneck. A steadier revenue stream follows from a different mix of work.
That shift requires deeper judgment as well as available time. NTPI levels, CTRS certification, and Tax Resolution Academy’s Certified Taxpayer Representative™ (CTR™) designation provide structured paths for developing expertise and signaling it credibly to clients. Freed hours make room to develop and apply advisory competence, while tax planning software supplies a separate layer for modeling the future scenarios and entity structures that advisory engagements require.
The strongest objection remains that automation improves speed without reducing judgment load. The EA retains professional responsibility for every return and every advisory position, even when systems or offshore preparers produce the first pass. The goal is responsibility exercised at the right level, through strategic review and client advisory.